


Most Texas homeowners policies cover wildfire damage. The harder question is whether you can keep that coverage at a price you can afford. This guide covers what insurers look at, what you can do about it and where to check the facts yourself.
In this guide
Does homeowners insurance cover wildfire damage?
The short answer
In most cases, yes. A standard Texas homeowners policy covers fire, including wildfire, up to your policy limits. Check your dwelling limit against today's rebuild cost, and read the exclusions.
The catch is renewal. Some carriers are more selective about homes near brush and cedar, and that can show up as a higher premium, lower limits or a nonrenewal. Your agent can tell you how your carrier treats your address.
What is happening with Texas wildfire coverage?
Texas has no statewide defensible-space requirement for homeowners. Inside Austin city limits, the City's Wildland-Urban Interface Code applies. Outside it, what you face is mostly your carrier's underwriting, not a state rule.
Underwriting is carrier by carrier
Hill Country counties such as Travis, Hays, Blanco and Llano have large areas of wildland-urban interface. Some carriers weigh nearby vegetation when they write or renew a policy. Others do not. We cannot tell you which is which for your address.
Ask your agent whether your carrier asks for proof of vegetation management, and what proof it accepts.
Nonrenewal has rules
The Texas Department of Insurance says a company must give written notice of nonrenewal. For nonrenewals after Jan. 1, 2026, the company must tell you why in writing. Notice periods depend on when the policy was bought or renewed. If you think a nonrenewal was unfair, you can file a complaint with TDI.
Details: Texas Department of Insurance, home insurance canceled or not renewed and the TDI home insurance guide.
If you cannot find coverage, the Texas FAIR Plan Association is an insurer of last resort. Its site says applicants need two declinations from other insurers. It does not compete with the private market, so treat it as a backstop.
What do insurers look for?
Carriers differ, so this is a general picture, not a rulebook. Three things come up most.
Distance from fuel to the house
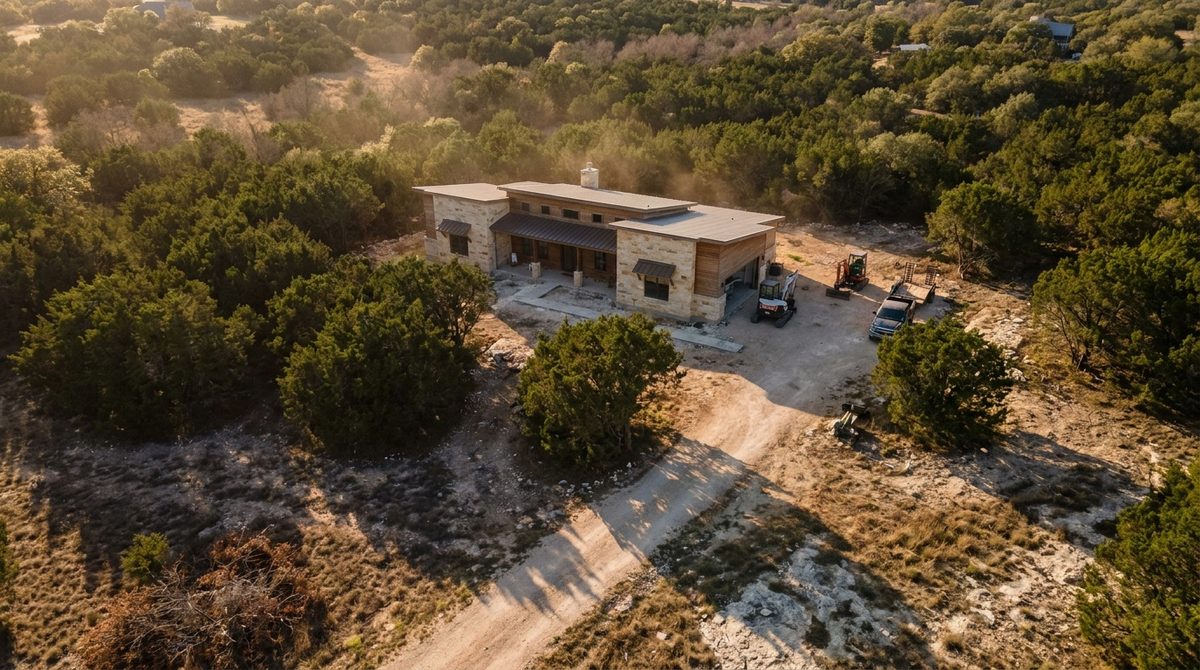
How close are brush, cedar and dry grass to the structure? Fuel near the walls, decks and vents is what ignites homes. The Insurance Institute for Business & Home Safety (IBHS) calls the first five feet around a house the most important area to clear of anything combustible (IBHS, Noncombustible Zone 0).
Defensible space
Defensible space means managed vegetation in home ignition zones: 0 to 5 feet, 5 to 30 feet, and 30 to 100 feet from the structure (NFPA 1140; Firewise USA is a community program built on the same zones). IBHS's Wildfire Prepared Home program also asks for 30 feet of defensible space.
Proof the work was done
A verbal "we cleared it" carries little weight. A simple file does more: dated before-and-after photos, the written scope and the contractor's invoice. We supply that for our jobs. Ask your carrier what it accepts before you spend money on any other format.
"Ask your agent before renewal what the carrier wants to see. It is much easier than answering a nonrenewal notice."
— Cody Baird, Owner
What can happen without defensible space?
Outcomes vary by carrier and policy. These are the ones homeowners near brush report most, and none is certain.
Higher premiums
A property flagged as higher risk can see a bigger increase at renewal than one that is not.
Lower dwelling limits
A lower limit leaves you insured for less than a rebuild costs. Compare your limit to current replacement cost each year.
Exclusions
A policy can carry endorsements or exclusions that limit what it pays. Ask your agent to point to any that touch fire.
Nonrenewal
If a carrier will not renew, you shop for new coverage, sometimes at a higher price. See the TDI links above and the FAIR Plan as a last resort.
Renewal coming up? We clear brush and cedar to the home ignition zones and leave you a simple file for your agent. See pricing or use the land clearing calculator. Defensible-space clearing runs $3,000–$4,500 per acre.
Request a Quote →What should you do before your next renewal?
Start with a call to your agent. Then work the checklist.
Pre-renewal checklist
- Ask your agent how your carrier views wildfire risk at your address, and what proof of mitigation it accepts
- Clear combustibles from the first 5 feet around the house, and thin and limb up vegetation out to 30 feet, then 100 feet
- Forestry mulching handles brush and cedar in the outer zones. Keep mulch out of the first 5 feet (IBHS)
- Keep dated before-and-after photos, the scope and the invoice in one folder
- Check your dwelling limit against current rebuild cost
- Annual maintenance scheduled so the work stays current
Timing
You have more choices before a nonrenewal notice than after one. Call your agent well ahead of the renewal date.
Frequently asked questions
Does homeowners insurance cover wildfire damage?
In most cases, yes. Standard Texas homeowners policies cover fire, including wildfire, up to policy limits. Read your policy for exclusions and limits, and ask your agent.
Can my homeowners insurance be cancelled because of wildfire risk?
Nonrenewal at the end of a term is the more common route than mid-term cancellation. Texas law requires written notice, and for nonrenewals after Jan. 1, 2026, the company must tell you why in writing. The Texas Department of Insurance explains your rights.
What documentation might an insurer ask for on defensible space?
It varies by carrier. Dated before-and-after photos, a written scope and the contractor's invoice are a reasonable starting file. Ask your agent what your carrier accepts.
What if I cannot find coverage?
Texas has a Texas FAIR Plan Association, an insurer of last resort. Applicants need two declinations from other insurers. Ask your agent whether you qualify.
Before the renewal notice
Talk to Your Agent.
Then Clear the Fuel.
We clear to the home ignition zones and keep a simple file of what was done. This is not insurance advice; talk to your agent about your policy.
Request a QuoteServing Austin, TX · Texas Hill Country
Prices reviewed: September 2026. Ranges for Austin and Central Texas; your site walk sets the final number. Last reviewed: September 2026.